Do I need commercial auto insurance if I only have one truck for my landscaping business?
The number of vehicles alone does not determine the coverage needed. If a vehicle is regularly used for landscaping or lawn care activities, its use, ownership, drivers, equipment transported and policy conditions should be evaluated to determine the appropriate auto coverage.
- Insurance type
- Commercial Auto Insurance
- Languages
- Spanish and English
- Documentation
- Options available depending on carrier and eligibility
- Free quote
- Yes, no obligation
- Carriers
- Several compared
- Phone
- 1-877-579-0587
Fast, free quotes with bilingual agents. No obligation.
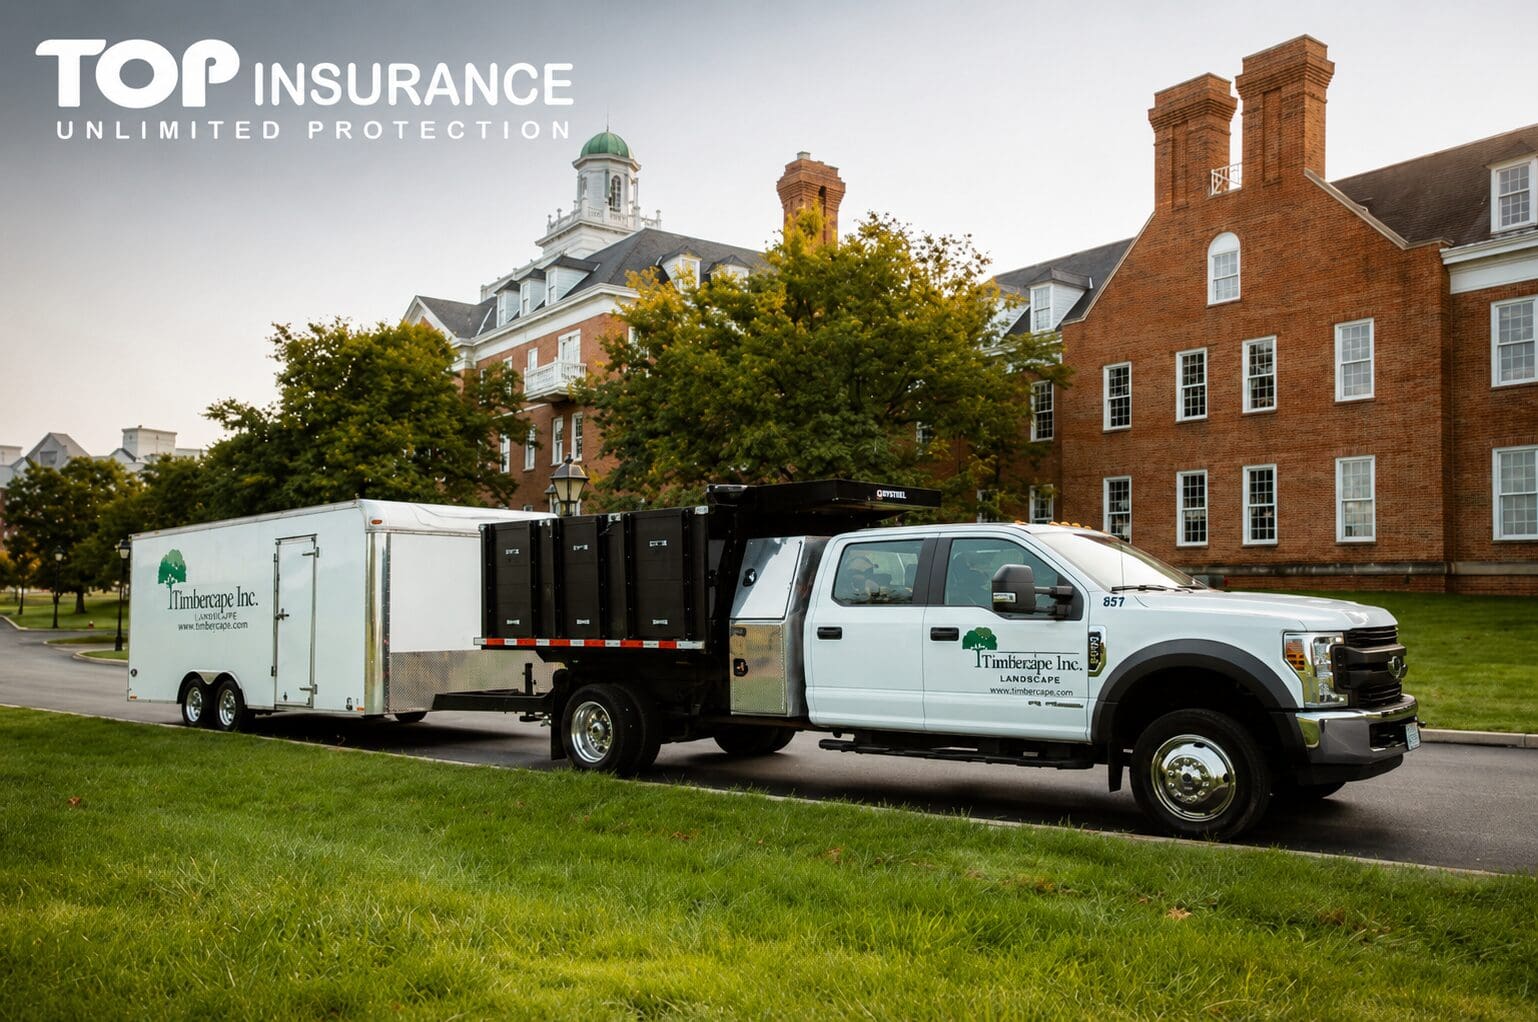
Landscaping, lawn care, and property maintenance businesses in Georgia depend entirely on their vehicles to operate: trucks loaded with mowers, trailers carrying heavy equipment, dump trucks for soil and debris, and vehicles that transport work crews from one client to another throughout the day. A single accident, equipment theft, or damage to a customer’s property can halt operations and cause significant financial losses if you don’t have the right protection in place.
Using a vehicle for business activities can create exposures different from personal use. A personal policy may limit or exclude certain commercial uses. The appropriate coverage depends on factors such as vehicle ownership, the business activity, drivers, frequency and type of use, goods or equipment transported and the policy terms. Georgia requires the applicable liability coverage to be maintained on vehicles subject to its insurance requirements. Certain commercial or motor carrier operations may also be subject to additional contractual, state or federal requirements.
In this guide prepared by top insurance llc, we explain in detail everything you need to know about commercial auto insurance for landscaping businesses in Georgia: essential coverages, legal requirements, cost factors, and how to fully protect your business.
Informational Notice: This content is for educational purposes only and does not constitute legal advice or an insurance policy. Terms, conditions, and coverage availability vary by insurer. Consult an agent at top insurance llc for a personalized quote.
Why Isn’t Your Personal Auto Insurance Enough?
When you use your truck or van to transport employees, tow trailers with heavy equipment, or travel between client properties for profit, you are engaging in commercial use of the vehicle. Personal auto policies contain specific exclusions for business activities, which means:
-
Claim Limitations: If you have an accident while working, your personal insurer may investigate the vehicle’s use and may limit or deny payment for damages if it determines undisclosed commercial activity.
-
Employee Coverage Gaps: Personal policies generally do not cover employees who drive the vehicle or who are transported as work passengers.
-
Insufficient Limits: Personal liability limits are usually too low for the level of exposure a commercial fleet with trailers, heavy equipment, and multiple drivers represents.
-
Towed Equipment Gaps: Your personal policy may not protect commercial trailers or the landscaping machinery you transport (mowers, blowers, irrigation equipment, etc.).
Essential Commercial Auto Coverages for Landscaping Businesses
1. Commercial Auto Liability
Covers bodily injury and property damage to third parties if one of your commercial vehicles causes an accident while heading to a property, transporting equipment, or performing business-related work. Georgia requires the applicable liability coverage to be maintained on vehicles subject to its insurance requirements, but for landscaping businesses with trucks and trailers, higher limits may be worth evaluating due to the risk of causing damage to high-value residential or commercial properties.
2. Physical Damage Coverage (Collision & Comprehensive)
-
Collision: May help pay for certain covered physical damage to the insured vehicle after a collision, subject to the deductible and policy terms.
-
Comprehensive: Protects against theft, vandalism, fire, falling trees or branches, and damage from severe storms, common in Georgia during hurricane and thunderstorm season.
3. Commercial Trailer Coverage (Trailer Interchange / Physical Damage)
Landscaping businesses often tow open or enclosed trailers to transport zero-turn mowers, light excavation equipment, and materials. Trailers should be reviewed specifically for liability, physical damage, equipment, ownership and whether they are scheduled on the policy. Coverage is not automatic just because a trailer is attached to the truck. This coverage may protect the trailer itself against damage, theft, or total loss, subject to policy terms.
4. Tools & Equipment in Transit Coverage (Inland Marine)
Tools and equipment being transported may require Inland Marine, Tools & Equipment or other specific coverage depending on the risk and the policy. An Inland Marine or “Contractor’s Equipment” coverage may protect:
-
Commercial mowers and cutting equipment.
-
Blowers, trimmers, and chainsaws.
-
Portable irrigation systems.
-
Hand tools and power tools.
-
Specialized landscaping equipment (aerators, spreaders, etc.).
5. Uninsured and Underinsured Motorist Coverage (UM/UIM)
Protects your employees and your business if an uninsured or underinsured third party causes an accident with one of your commercial vehicles.
6. Medical Payments Coverage (MedPay / Commercial PIP)
May cover certain immediate medical expenses for the driver and occupants (employees) of the commercial vehicle in the event of an accident, subject to policy terms.
7. Hired and Non-Owned Auto Coverage (HNOA)
Hired and Non-Owned Auto may provide certain liability protection for exposures related to vehicles the business does not own, subject to the policy definitions, limits, exclusions and conditions. It does not automatically replace the vehicle owner's policy.
8. Fleet Roadside Assistance
Towing and mechanical assistance service for trucks and trailers that break down on the road, minimizing downtime and lost income.
Other Complementary Coverages Your Landscaping Business Should Consider
In addition to commercial auto insurance, a full-service landscaping business in Georgia may consider:
-
General Liability: Covers third-party bodily injury or property damage that doesn’t involve a vehicle (for example, damaging an irrigation pipe while mowing or injuring a customer with cutting equipment).
-
Workers’ Compensation: Mandatory in Georgia for businesses with three or more employees. Covers work-related injuries to your crew, common in jobs involving cutting machinery and heat exposure.
-
Commercial Umbrella: An additional layer of liability protection above the limits of your commercial auto and general liability policies.
-
Equipment Breakdown Coverage: Protects against mechanical or electrical failures of stationary equipment, such as installed irrigation systems.
Legal Requirements for Landscaping Businesses in Georgia
-
Commercial vehicle registration: Vehicles used for business purposes may need to be registered and insured appropriately based on the use, ownership and applicable requirements.
-
Minimum liability limits: Georgia requires the applicable liability coverage to be maintained on vehicles subject to its insurance requirements. Certain operations may have higher requirements, especially if the vehicle’s gross weight (GVW) exceeds certain thresholds.
-
Commercial Driver’s License (CDL): May be required if operating trucks above a certain gross combined vehicle weight (GCVW), such as large dump trucks with heavy trailers.
-
Certificate of Insurance (COI): Many commercial clients, HOAs (homeowners associations), and property management companies require a COI before allowing access to their properties.
Factors That Influence the Cost of Commercial Auto Insurance for Landscaping
-
Number and type of vehicles: Light trucks, dump trucks, trucks with cranes or flatbeds.
-
Value and type of trailers and towed equipment.
-
Number of employees and authorized drivers, including their driving record (MVR).
-
Operating radius: Businesses operating only within Gwinnett County will have a different risk profile than those covering multiple counties or states.
-
Years in business and claims history.
-
Selected coverage limits and deductibles.
-
Total value of equipment insured under Inland Marine.
Common Mistakes to Avoid
| Common Mistake | Consequence / Risk |
|---|---|
| Using personal auto insurance for work vehicles | Possible claim limitations or exclusions and possible policy cancellation. |
| Not reviewing trailer coverage specifically | Possible gaps in liability, physical damage or equipment coverage for the trailer. |
| Not including Inland Marine or Tools & Equipment coverage | Possible out-of-pocket replacement costs for stolen or damaged mowers, blowers, and tools. |
| Not disclosing all employees who drive | Possible coverage exclusion if an unauthorized driver causes an accident. |
| Skipping the Certificate of Insurance (COI) | Loss of commercial contracts and HOA jobs requiring proof of coverage. |
| Not carrying Workers’ Compensation | Possible state penalties and personal liability for uncovered work-related injuries. |
Frequently Asked Questions (FAQ)
Do I need commercial auto insurance if I only have one truck for my landscaping business?
The number of vehicles alone does not determine the coverage needed. If a vehicle is regularly used for landscaping or lawn care activities, its use, ownership, drivers, equipment transported and policy conditions should be evaluated to determine the appropriate auto coverage.
Does my commercial auto insurance cover the mowers and tools I transport?
Tools and equipment being transported may require Inland Marine, Tools & Equipment or other specific coverage depending on the risk and the policy. Additional coverage may be needed to protect equipment transported inside the vehicle or trailer against theft, damage, or loss.
What happens if an employee uses their own car to run a business errand and has an accident?
Without Hired & Non-Owned Auto coverage, your business could face certain liability exposures. Hired and Non-Owned Auto may provide certain liability protection for exposures related to vehicles the business does not own, subject to the policy definitions, limits, exclusions and conditions. It does not automatically replace the vehicle owner's policy.
Is Workers’ Compensation mandatory for my landscaping business in Georgia?
If your business has three or more employees (including part-time), Georgia law may require you to maintain an active Workers’ Compensation policy. Consult an agent for your specific situation.
How do I get a Certificate of Insurance (COI) to work with HOAs or commercial clients?
Once your commercial auto and general liability policies are active with top insurance llc, we can issue your Certificate of Insurance so you can meet your clients’ contractual requirements.
Does commercial auto insurance cover damage I cause to a client’s property while working?
Commercial auto insurance may cover certain damage related to vehicle use (for example, hitting a fence while maneuvering). Damage caused by the work itself (such as damaging the lawn or pipes) may be addressed under your General Liability policy, not your auto policy, subject to policy terms.
Protect Your Landscaping Business with top insurance llc
At top insurance llc, we understand the specific needs of landscaping businesses in Georgia. We work with you to design a complete commercial insurance package that protects your vehicles, equipment, employees, and assets against any unforeseen event.
We help you structure:
-
Commercial auto insurance for trucks, vans, and trailers.
-
Inland Marine coverage for landscaping tools and machinery.
-
General Liability and Workers’ Compensation.
-
Certificates of Insurance (COI) for contracts with clients, HOAs, and property managers.
-
Commercial Umbrella insurance for additional protection.
Get Your Commercial Insurance Quote Today
-
Commercial & Business Insurance: comercial.topinsus.com
-
Auto Insurance Quotes: auto.topinsus.com
-
General Quotes: cotiza.topinsus.com
-
Direct Phone Line: 877-579-0587
-
Website: www.topinsus.com
Visit us at our offices in Duluth and Lawrenceville, serving all of Georgia and licensed in FL, TN, IN, SC, AL, and TX.
Conclusion
A landscaping business in Georgia depends directly on its vehicles, trailers, and equipment to generate income day after day. Failing to properly protect these assets with comprehensive commercial auto insurance can jeopardize the continuity of your operation in the event of an accident, theft, or customer claim.
Contact top insurance llc today and get coverage designed specifically for the needs of your landscaping business, with the peace of mind of expert support at every step.
TOP Insurance LLC is a licensed independent insurance agency serving Georgia, Florida, South Carolina, Tennessee, Alabama, Indiana and Texas. Our bilingual team of licensed agents compares options from several carriers to find an alternative that fits your needs and budget. With offices in Duluth, Lawrenceville and Gainesville, GA, we specialize in auto, home, life, health and commercial insurance for the Hispanic community and all residents. Some carriers may offer options for applicants with an ITIN, consular ID, foreign passport or foreign license; required documentation and eligibility depend on each carrier.
Ready for your free quote?
Our bilingual agents help you compare options from multiple carriers to find an alternative that fits your needs and budget. Same-day response, no obligation.