Which employers in Dougherty County are required to carry workers' compensation insurance?
Under Georgia state law, any business that regularly employs three or more workers must carry workers' compensation insurance. This mandate applies to full-time, part-time, and seasonal employees across all business structures, including LLCs, corporations, and partnerships.
- Insurance type
- Workers' Compensation
- Languages
- Spanish and English
- Documents
- ITIN & consular ID accepted
- Free quote
- Yes, no obligation
- Carriers
- 30+ compared
- Phone
- 1-877-579-0587
Free quote in 60 seconds with bilingual agents. No obligation.
Workers' Compensation Insurance in Dougherty County, GA: A 2026 Employer Guide
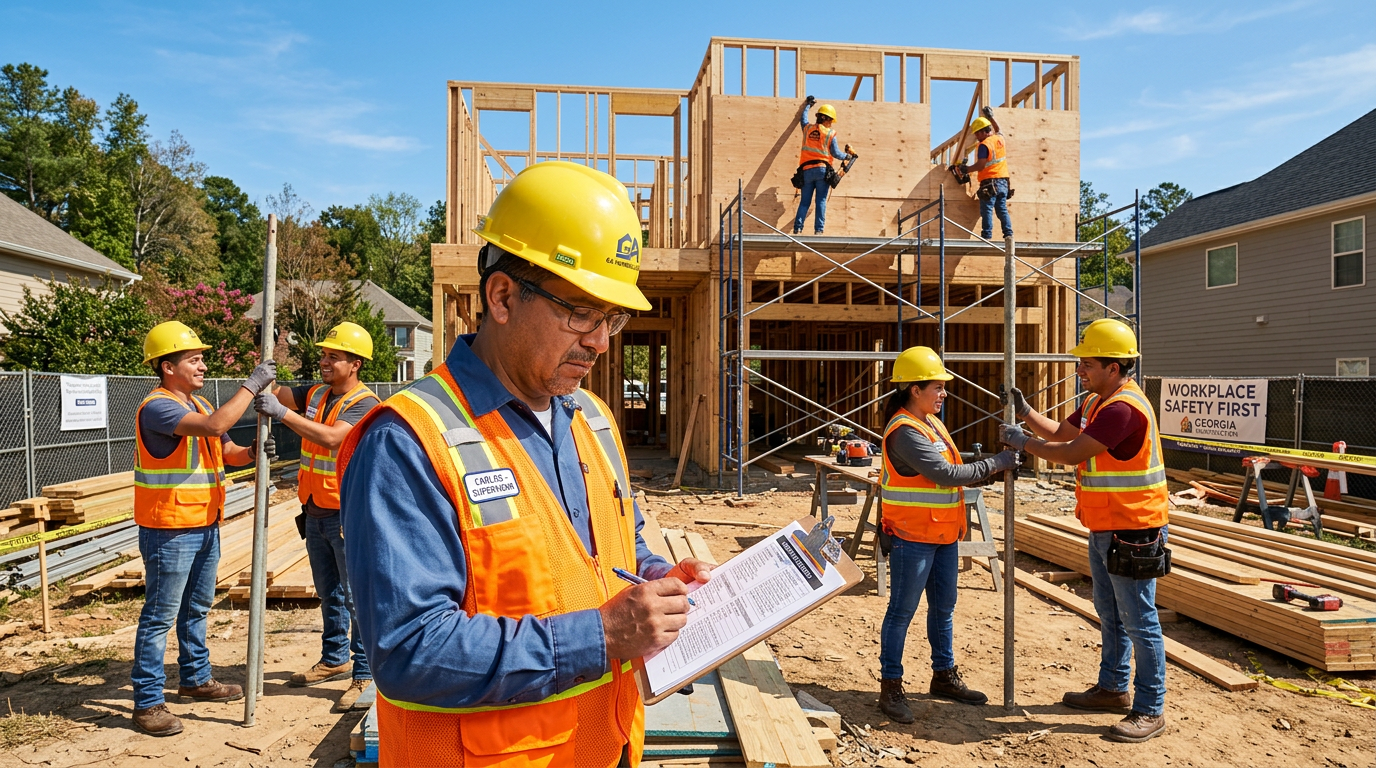
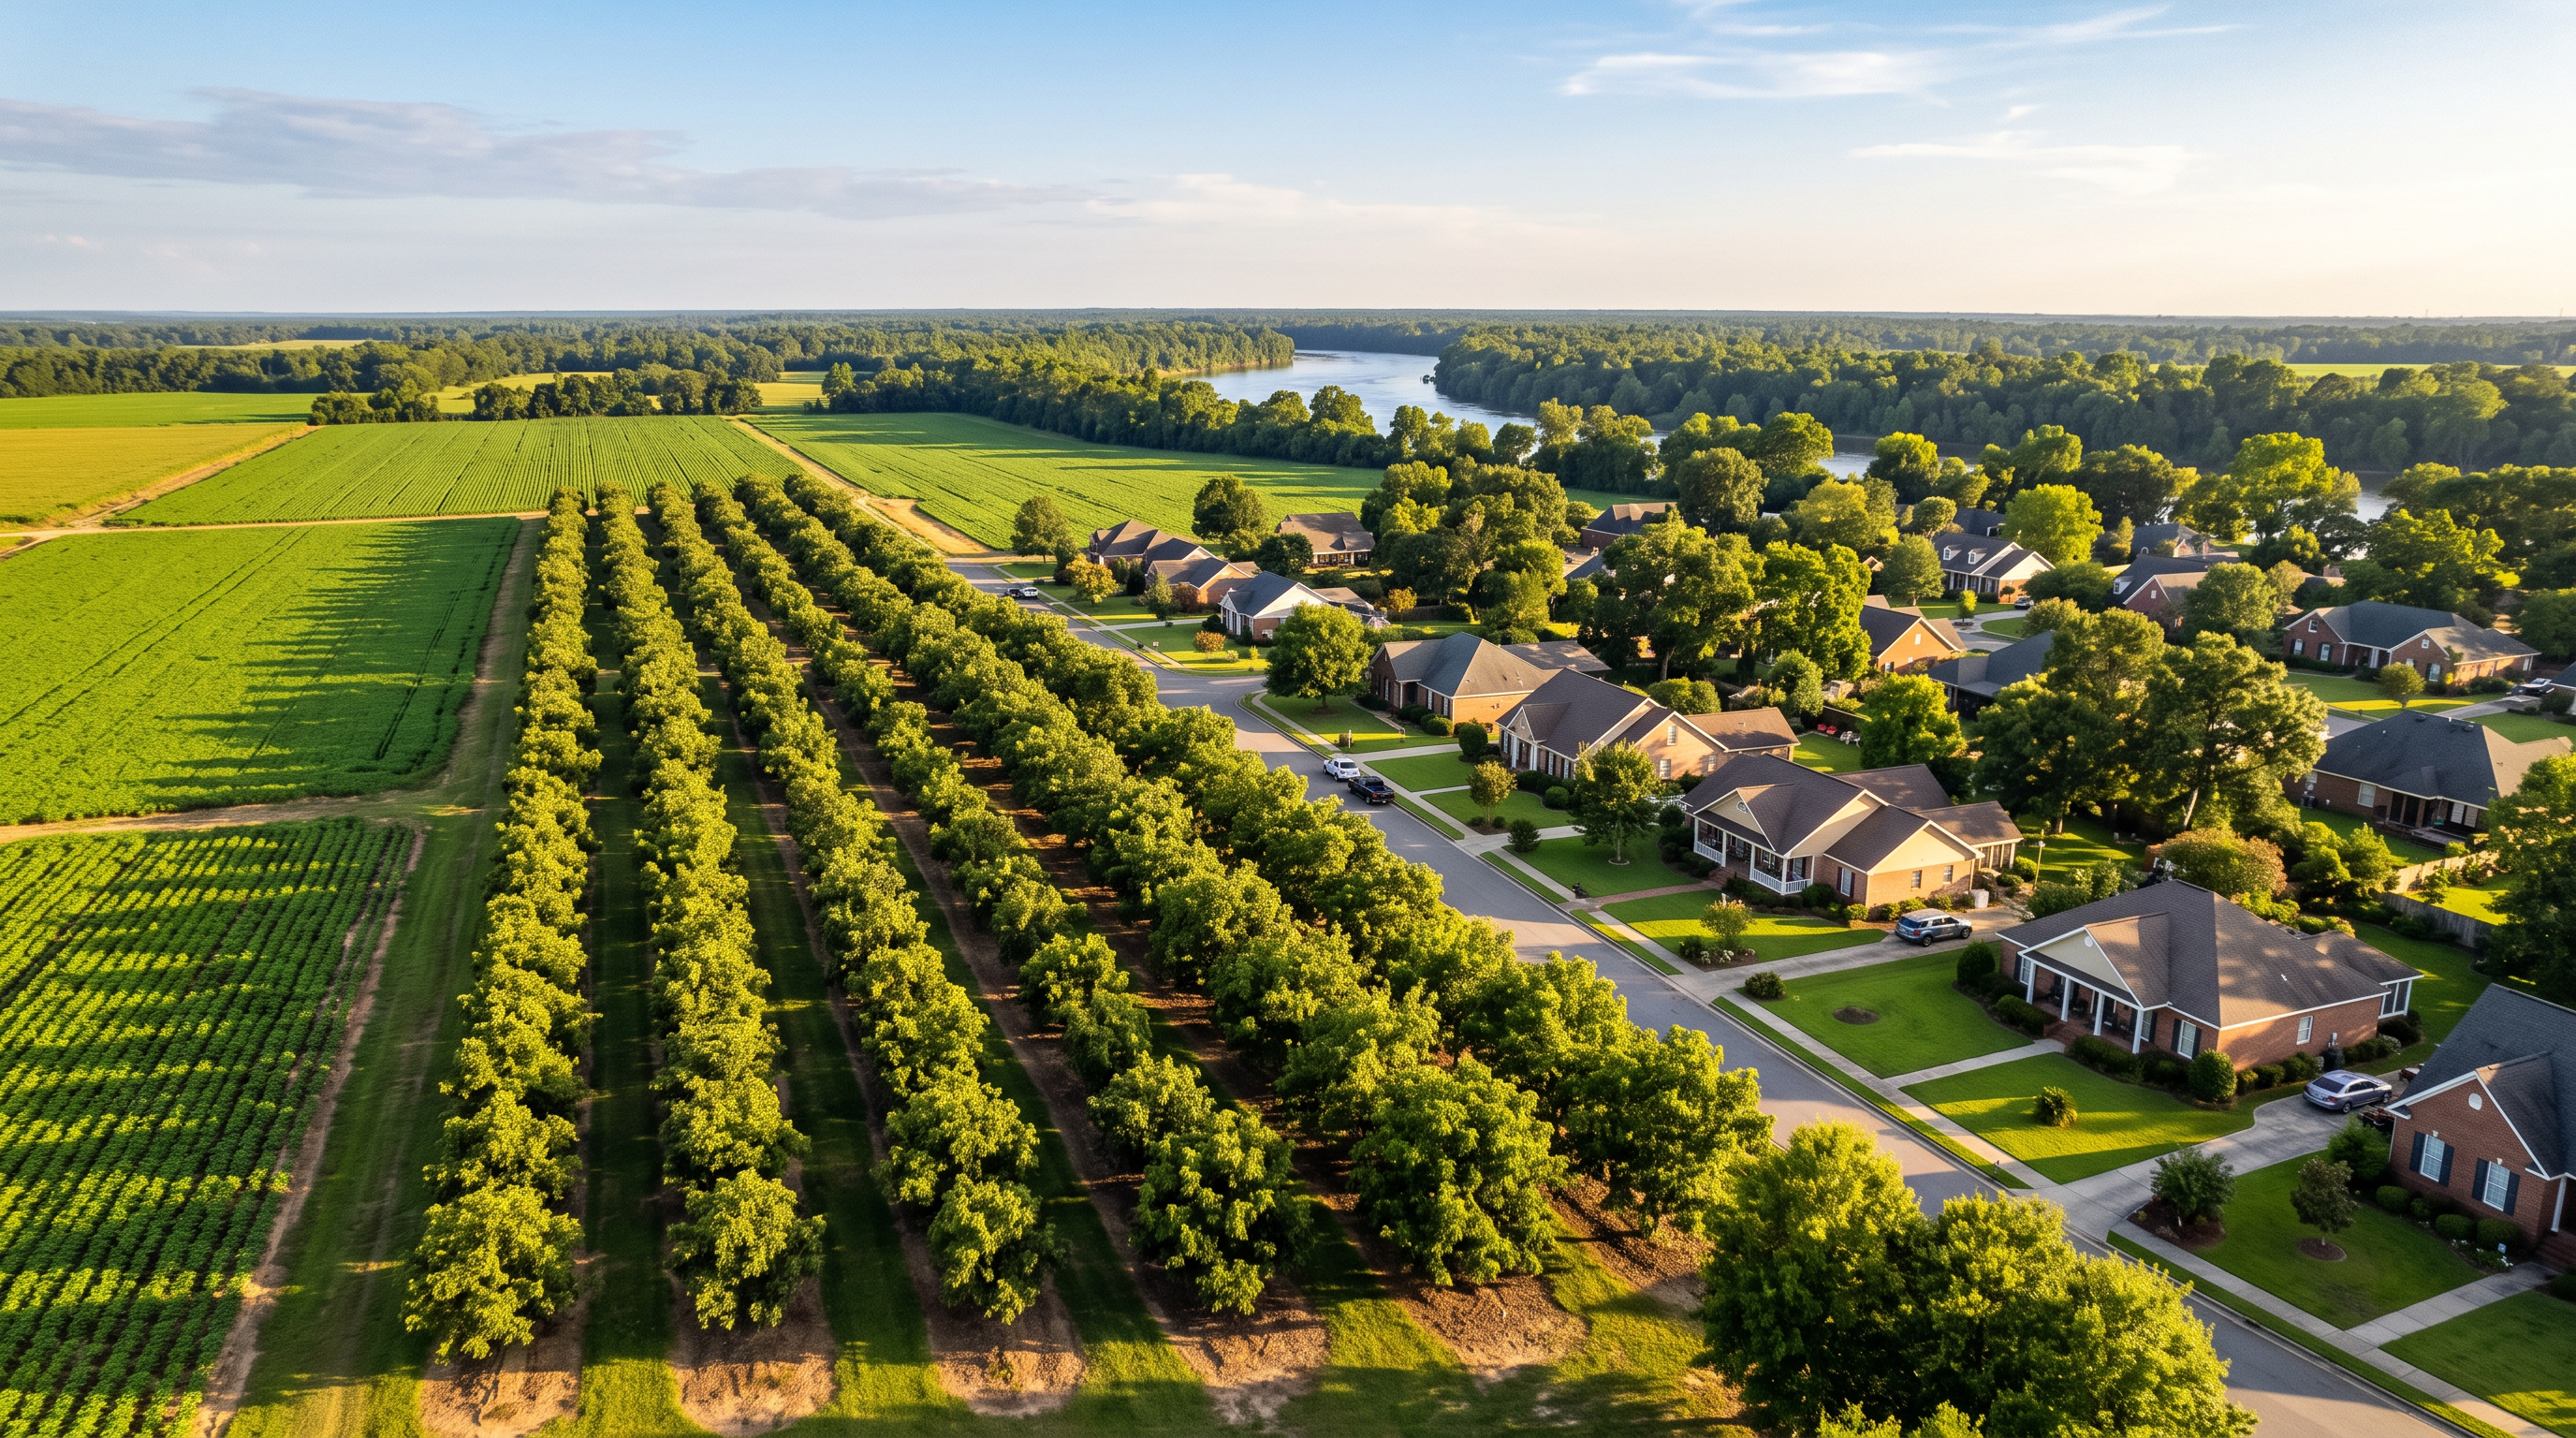
Dougherty County — centered on Albany — is home to Southwest Georgia’s hub anchors the economy, driven by agriculture (pecans and peanuts), the Marine Corps Logistics Base Albany, Phoebe Putney Health System, and food processing, with a growing Hispanic workforce in agriculture, construction, and food service. If you employ three or more workers in Georgia, workers' compensation insurance is required by law.
At Top Insurance LLC we help Dougherty County employers get compliant, affordable workers' comp with full bilingual support. This guide covers the rules, costs, and how to get covered fast.
Georgia Workers' Comp Law: Who Must Carry It?
Under O.C.G.A. § 34-9-2, any Georgia employer with 3 or more employees (full-time, part-time, or seasonal) must carry workers' compensation. This includes:
-
Sole proprietors and partnerships with 3+ workers.
-
LLCs and corporations with any 3+ employees.
-
Subcontractors — if they lack coverage, the general contractor becomes liable.
Penalties: Operating without required coverage is a misdemeanor. Each day uninsured can carry fines of $1,000–$10,000, and you can be personally liable for all medical bills and lost wages.
What Does Workers' Comp Cover?
-
Medical expenses: ER visits, surgery, rehab, prescriptions — from dollar one, no deductible for the employee.
-
Lost wages: Typically two-thirds of the worker's average weekly wage while they recover.
-
Disability benefits: Temporary or permanent, partial or total.
-
Death benefits: Burial costs and survivor income for the worker's family.
-
Employer liability protection: Shields you from most lawsuits related to the workplace injury.
What Affects Your Premium?
-
Class code: Higher-risk trades (roofing, concrete, trucking) pay more than office work.
-
Payroll: Workers' comp is priced per $100 of payroll, so your total payroll in Dougherty County directly determines your base premium.
-
Claims history (Experience Modifier): Fewer claims = lower mod = lower premium.
-
Safety programs: Drug-free workplace and return-to-work programs can earn discounts.
Workers' Comp for Employers Across Dougherty County
From Albany to the surrounding communities, we insure employers in every corner of Dougherty County:
-
Albany (Downtown & East Albany): The county seat — retail, restaurants, contractors, and Hispanic-owned businesses across the city.
-
Flint River neighborhoods: Homes and businesses near the river where flood awareness is essential after the historic floods.
-
US-19 & US-82 corridors: Warehouses, food processing, trucking, and agricultural vendors.
-
Rural Dougherty County: Pecan groves, farms, and agricultural operations where local risk factors matter.
How to Lower Your Workers' Comp Costs
-
Classify correctly: Misclassifying workers inflates your premium. We audit your class codes for accuracy.
-
Implement safety programs: A written safety plan and drug-free workplace certification can earn 5%+ discounts.
-
Report claims fast: Timely reporting reduces claim severity and keeps your experience modifier low.
-
Pay-as-you-go: Monthly premium based on actual payroll avoids large audits and cash-flow surprises.
-
Compare carriers: Top Insurance compares 30+ carriers to find the best rate for your trade and payroll.
Why Dougherty County Employers Choose Top Insurance
-
100% bilingual: We explain coverage in English and Spanish — no confusion.
-
Same-day certificates: We can issue your COI the same day so you can start a job immediately.
-
ITIN, passport, consular ID accepted: We work with all valid identification.
-
30+ carriers: We find the right carrier for your trade and budget.
Call (877) 579-0587 or WhatsApp us for a free bilingual quote today.
This article is for educational purposes only and does not constitute legal or financial advice. Consult a licensed professional for your specific situation.
Explore your coverage options
Frequently Asked Questions
Which employers in Dougherty County are required to carry workers' compensation insurance?
Under Georgia state law, any business that regularly employs three or more workers must carry workers' compensation insurance. This mandate applies to full-time, part-time, and seasonal employees across all business structures, including LLCs, corporations, and partnerships.
Are seasonal or agricultural workers counted toward the coverage threshold?
Yes, Georgia law counts seasonal, part-time, and temporary staff toward the three-employee threshold required for mandatory coverage. Employers in sectors like agriculture and food processing must include these workers when determining their statutory obligations.
What penalties do Dougherty County employers face for failing to maintain required coverage?
Failing to carry required workers' compensation insurance is classified as a misdemeanor under Georgia law. Non-compliant employers can face civil penalties ranging from $1,000 to $10,000 per violation, along with potential personal liability for employee medical expenses and lost wages.
How does workers' compensation apply to independent contractors and subcontractors?
If a subcontractor does not carry active workers' compensation coverage, the general contractor may be held legally liable for injuries sustained by that subcontractor or their crew. Employers should verify certificates of insurance for all 1099 workers and subcontractors to avoid assumption of statutory employer liability.
What benefits does a standard workers' compensation policy provide?
A standard policy provides statutory medical benefits, covering authorized treatment and rehabilitation costs related to job-related injuries or illnesses. It also provides indemnity benefits for temporary or permanent wage replacement, as well as death benefits to qualifying dependents in fatal workplace incidents.

TOP Insurance LLC is a licensed independent insurance agency serving Georgia, Florida, South Carolina, Tennessee, Alabama, Indiana and Texas. Our bilingual team of licensed agents compares rates from 30+ carriers to find the best coverage at the best price. With offices in Duluth, Lawrenceville and Gainesville, GA, we specialize in auto, home, life, health and commercial insurance for the Hispanic community and all residents. We accept ITIN, consular ID and foreign licenses.
Ready for your free quote?
Our bilingual agents help you find the best coverage at the best price. Same-day response, no obligation.