Is renters insurance required by law in Georgia?
No. No U.S. state, including Georgia, requires renters insurance by law. However, a landlord may require it in the lease and may ask for minimum liability limits or to be listed as an interested party.
- Insurance type
- Home Insurance
- Languages
- Spanish and English
- Documents
- ITIN & consular ID accepted
- Free quote
- Yes, no obligation
- Carriers
- 30+ compared
- Phone
- 1-877-579-0587
Free quote in 60 seconds with bilingual agents. No obligation.
Building a home inventory before a loss can save time and stress when you need to file a renters insurance claim. If a covered theft, fire, or other loss happens, photos, receipts, and serial numbers help prove what you owned and what it was worth.
In Georgia, and for clients in Florida, Texas, South Carolina, Tennessee, Alabama, and Indiana, TOP Insurance LLC compares options from more than 30 insurers with bilingual service, 3 Georgia offices in Duluth, Lawrenceville, and Gainesville, and options for people who use an ITIN. Call 1-877-579-0587 for a free quote.
Why a home inventory matters
The landlord's policy covers the building and the landlord's liability. It does not cover your belongings, your personal liability, or your life if a covered loss makes the unit uninhabitable. That is why renters insurance, often called an HO-4 policy, is so important. It usually includes personal property, personal liability, medical payments to others, and loss of use or ALE when you cannot live in the unit after a covered loss.
A good inventory helps you show what you owned, when you owned it, and the condition it was in before the loss. That makes the claims process smoother and more accurate.
How to build your inventory with your phone
1. Walk through the home room by room
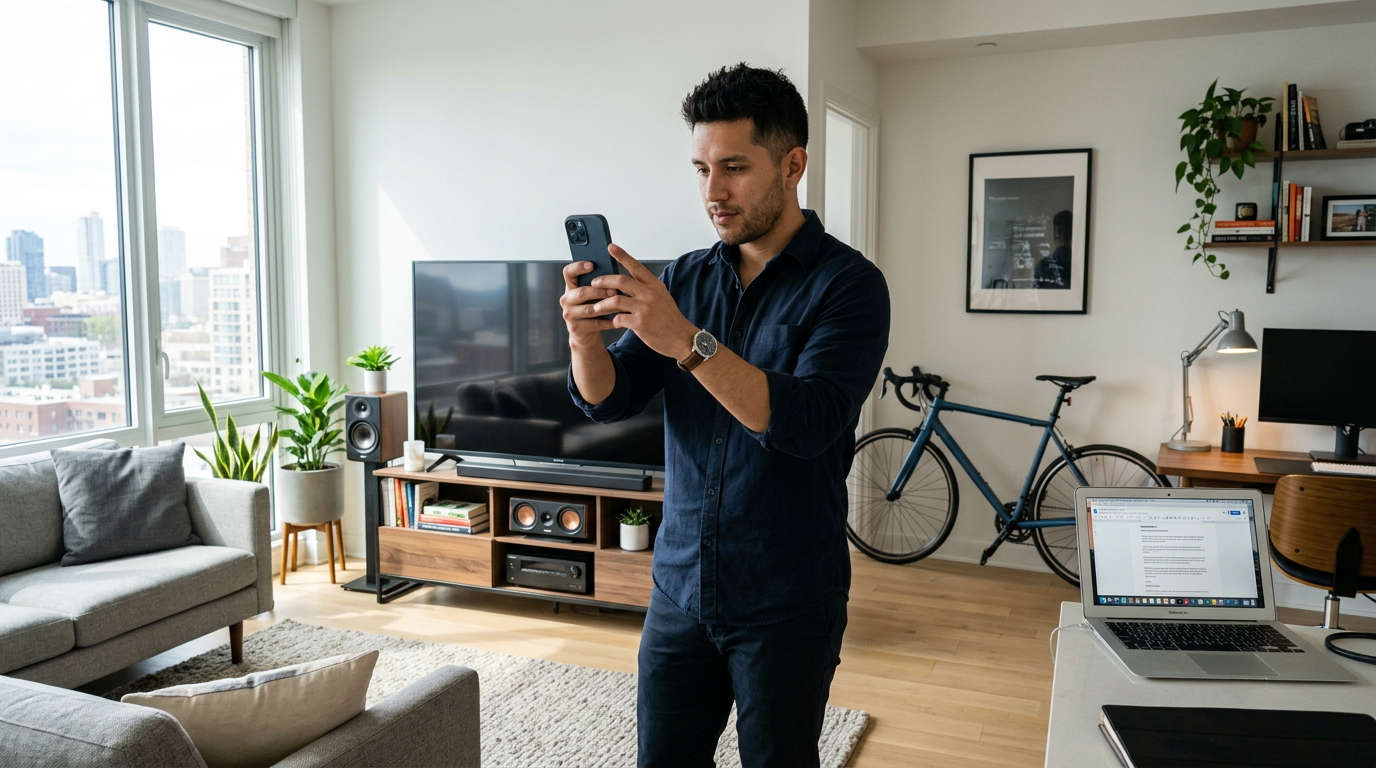
Use your phone camera to record a slow video of every room. Start with the living room, then bedrooms, kitchen, bathroom, closets, garage, storage areas, and any other space where you keep belongings. Speak as you go and describe what you are seeing.
You can also take individual photos of important items. A mix of video and still photos gives you both broad coverage and detailed proof.
2. Focus on the items that matter most
You do not need to record every spoon, but you should document the main categories:
- Furniture
- Clothing and shoes
- Electronics and devices
- Computers, tablets, and phones
- Small appliances
- Jewelry, watches, and valuable items
- Tools, bicycles, and sports equipment
- Items stored in closets, cabinets, and boxes
For higher-value items, include the brand, model, serial number, and any receipt you have. Those details can be very helpful when your insurer reviews the claim or calculates replacement.
3. Save receipts and extra proof
If you have receipts, order confirmations, manuals, or photos of the item when it was new, store them with your inventory. If you do not have a receipt, a clear photo and an accurate description are still better than nothing.
It also helps to note when you bought the item and, if you know it, what you paid for it. Do not guess. Only include information you can verify.
4. Store everything in the cloud
Your inventory should be kept outside the home. Save a copy in the cloud, in your email, or in a protected digital folder. If a fire, theft, or major loss destroys the home, your evidence should survive too.
5. Update it regularly
Review your inventory whenever you buy something important, move, or significantly change what you keep in the home. An updated inventory is far more useful than an old one.
What renters insurance usually covers
An HO-4 policy often protects personal property against named perils such as fire, smoke, theft, vandalism, lightning, and some water damage from plumbing. It can also include personal liability, medical payments to others, and loss of use or ALE if the home becomes uninhabitable after a covered event.
It normally does not cover flood, earthquake, pests, normal wear and tear, or intentional damage. High-value items such as jewelry may also have sublimits and may need an endorsement.
Also remember that the landlord's policy does not replace your own renters coverage. Even when the landlord is insured, your belongings still need protection.
What to do before you file the claim
1. File a police report for theft
If something was stolen, file a police report as soon as possible. Your insurer may ask for it when reviewing the claim. Keep a copy of the report or at least the case number.
2. Take photos and videos of the damage
Document the damage before cleaning or throwing anything away. Take photos from several angles and, if possible, record a video of the affected area. Capture visible damage to furniture, walls, floors, clothing, electronics, and anything else that was harmed.
3. Prevent further damage
If it is safe to do so, take reasonable steps to prevent more damage. For example, cover a broken window, shut off a water leak, or move undamaged items away from the affected area. Save receipts for any necessary emergency repairs or protective measures.
4. Notify your insurer quickly
Report the loss as soon as you can. Explain what happened, when it happened, what was damaged, and whether you filed a police report. The sooner you report it, the easier it is to follow the correct claims process.
How claim payment is calculated
Before payment, the deductible is subtracted from each property claim payment. The valuation method also matters:
- Actual cash value, or ACV, subtracts depreciation.
- Replacement cost pays what it takes to buy a new equivalent item.
That means two policies can pay differently for the same item. A replacement cost policy may pay more than an ACV policy, but the price of the policy also varies based on the state, ZIP code, coverage amount, deductible, ACV or replacement cost coverage, and claims history.
That is why it is smart to compare quotes for free before you buy.
What to know about roommates and household members
Many insurers cover only the named insured and family members who live with that person. Roommates usually need their own policy, although some companies allow them to be added. If you share a home, confirm this before a loss happens so there are no surprises during a claim.
Ways to save and find better coverage
If you already have auto insurance, bundling renters insurance with your auto policy may create savings on both. Also, some insurers accept an ITIN or passport instead of a Social Security number. TOP Insurance compares companies that accept this documentation and helps you find the best fit for your needs.
As a bilingual agency focused on the Hispanic community, TOP Insurance LLC works with more than 30 carriers and has 3 offices in Georgia: Duluth, Lawrenceville, and Gainesville. We also serve clients in Florida, Texas, South Carolina, Tennessee, Alabama, and Indiana.
Quick recap
- Use your phone to take photos and video of your home.
- Store receipts, serial numbers, and proof in the cloud.
- For theft, file a police report.
- Document the damage before cleaning or discarding items.
- Prevent further damage if it is safe.
- Notify your insurer as soon as possible.
- Review your deductible and whether your policy pays ACV or replacement cost.
Preguntas frecuentes
Is renters insurance required by law in Georgia?
No. No U.S. state, including Georgia, requires renters insurance by law. However, a landlord may require it in the lease and may ask for minimum liability limits or to be listed as an interested party.
Does the landlord's policy cover my belongings?
No. The landlord's policy covers the building and the landlord's liability, not your belongings or your personal liability. That is why you need your own renters policy.
What happens if I have a roommate?
Many insurers cover only the named insured and family members living with that person. Roommates usually need their own policy, although some companies allow them to be added. It is best to confirm this before moving in together.
Why might my payment be different from what I originally paid?
Because the claim may be settled on ACV, which subtracts depreciation, or on replacement cost, which pays what is needed to buy a new equivalent item. The deductible and the coverage you chose also affect the payment.
Related renters insurance guides- What Renters Insurance Covers (and What It Doesn't): Complete 2026 Guide
- Renters Insurance With an ITIN or Without a Social Security Number (2026)
- Is Renters Insurance Required? What Your Landlord Can Require (2026)
- Renters Insurance vs. Landlord Insurance: Who Covers What When You Rent
Get a free renters insurance quote
At TOP Insurance we compare 30+ carriers to find your renters policy at the best price, accept ITIN and serve you in English or Spanish. Call 1-877-579-0587 or visit our renters insurance page.

TOP Insurance LLC is a licensed independent insurance agency serving Georgia, Florida, South Carolina, Tennessee, Alabama, Indiana and Texas. Our bilingual team of licensed agents compares rates from 30+ carriers to find the best coverage at the best price. With offices in Duluth, Lawrenceville and Gainesville, GA, we specialize in auto, home, life, health and commercial insurance for the Hispanic community and all residents. We accept ITIN, consular ID and foreign licenses.
Ready for your free quote?
Our bilingual agents help you find the best coverage at the best price. Same-day response, no obligation.