
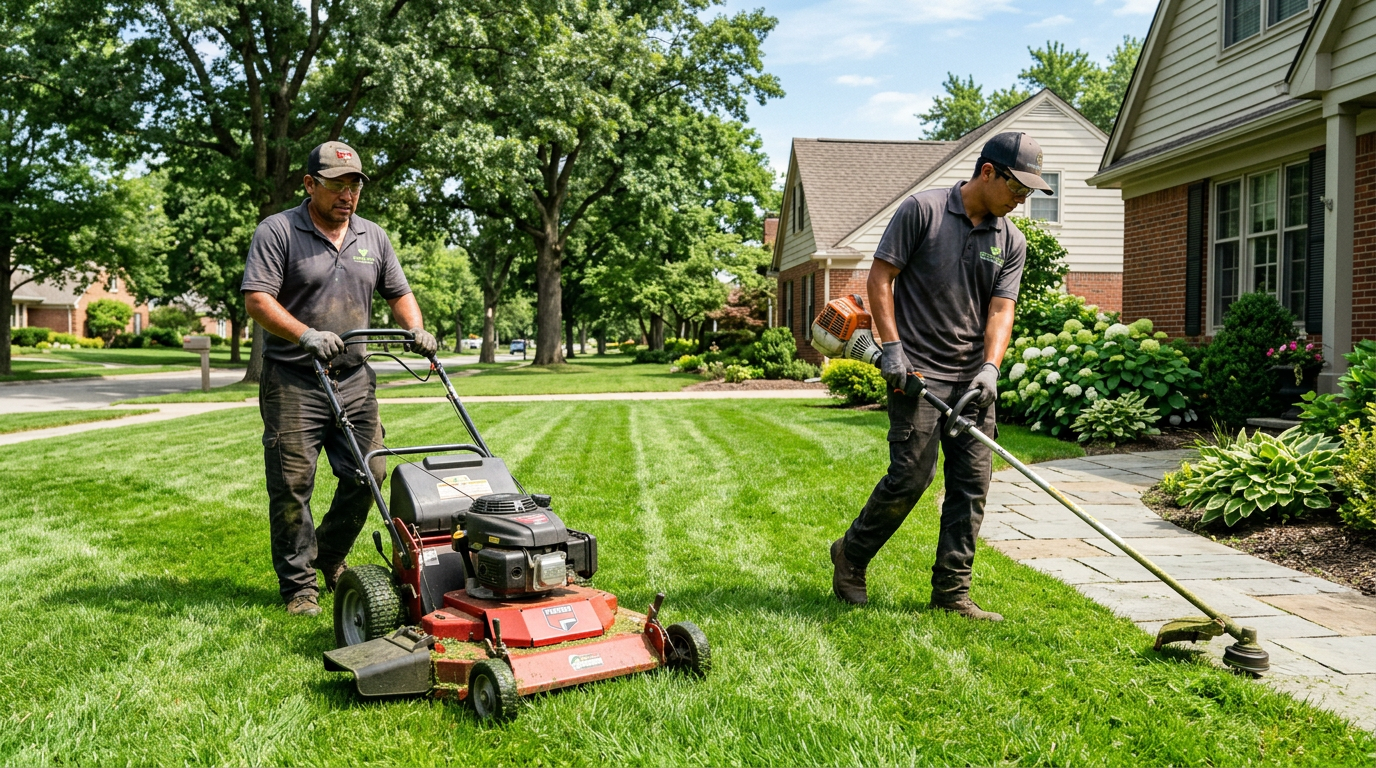
Do landscapers need workers' comp in Florida?
Yes, if you have one or more employees (construction). Machinery, heat, and cutting injuries make this coverage essential.
- Insurance type
- General Liability
- Languages
- Spanish and English
- Documentation
- Options available depending on carrier and eligibility
- Free quote
- Yes, no obligation
- Carriers
- Several compared
- Phone
- 1-877-579-0587
Fast, free quotes with bilingual agents. No obligation.
Landscaping businesses in Florida work with heavy equipment, sharp tools, and chemicals — and a single flying rock from a mower can break a window or injure a bystander. Between property damage, injuries, trailers full of expensive equipment, and herbicide exposure, the right insurance keeps a bad day from ending your season. This guide explains the coverage a Florida landscaping business needs in 2026 and the mistakes that leave you exposed.
Quick Answer: Landscaping Business Insurance in Florida (2026)
- General liability covers property damage and injuries — like a rock thrown by a mower breaking a window.
- Workers' compensation is required in Florida for construction businesses with one or more employees (including seasonal part-timers).
- Commercial auto covers trucks and trailers hauling crews and equipment.
- Inland marine (equipment) coverage protects mowers, trimmers, and tools on-site or in transit.
- If you apply chemicals, ask about herbicide/pesticide coverage — it is often excluded by default.
What Insurance a Landscaping Business Needs in Florida
Landscaping combines property-damage risk, heavy equipment, vehicle exposure, and chemical application. Here are the core coverages and why each matters for a Florida landscaping business.
| Policy | What it covers | Why a Landscaping Business needs it |
|---|---|---|
| General Liability | Property damage and third-party injuries | A mower throws a rock through a window or a client trips over equipment |
| Workers' Compensation | Medical bills and lost wages for injured crew | Required in Florida construction at 1+ employee; cuts, heat, and machinery injuries are common |
| Commercial Auto | Accidents involving trucks and trailers | Personal auto excludes hauling crews and equipment to job sites |
| Inland Marine (Equipment) | Theft or damage of mowers, trimmers, and tools | Trailer theft and job-site loss of equipment are frequent claims |
| Herbicide/Pesticide | Claims from chemical application | Standard liability often excludes chemical drift or misapplication |
The Most Common Insurance Mistakes for Landscaping Businesses in Florida
Mistake #1: Assuming general liability covers thrown-object damage
Damage from a rock thrown by a mower is common — confirm it is covered, because some policies limit or exclude these claims.
Mistake #2: Not insuring equipment on trailers
Mowers and tools stolen from a trailer are a top loss for landscapers. Inland marine coverage protects equipment on-site and in transit.
Mistake #3: Skipping workers' comp with a seasonal crew
Florida requires construction businesses to carry workers' compensation with one or more employees, including seasonal part-timers. Machinery injuries make this essential.
Mistake #4: Applying chemicals without the right coverage
Herbicide and pesticide claims are often excluded from standard liability. If you apply chemicals, you likely need a specific endorsement.
Mistake #5: Using personal auto for trucks and trailers
Personal auto excludes business use. If you crash hauling equipment, the claim can be denied — you need commercial auto.
Landscaping Business Risks in Florida
Florida landscapers face property damage from mowers and equipment, injuries from machinery and heat, theft of gear from trailers, and liability from chemical application. Florida's long growing season and frequent storm cleanup keep crews busy — and exposed — much of the year. Commercial clients and HOAs typically require proof of general liability and, where applicable, workers' comp, so layered coverage is what keeps you eligible for steady contracts.
How to Save on Landscaping Business Insurance in Florida
- Bundle general liability and property into a Business Owner's Policy (BOP).
- Lock and track equipment on trailers to reduce theft claims.
- Document chemical-application training and licensing.
- Adjust coverage seasonally as your crew size changes.
- Compare quotes from multiple carriers through an independent agency.
Why Choose TOP Insurance in Florida
TOP Insurance has helped over 10,000 families and business owners across Georgia, Florida, Texas, South Carolina, Tennessee, Alabama, and Indiana find coverage options that fit their needs and budget. Our licensed, bilingual agents compare quotes from several carriers, so you never have to shop one company at a time.
Because we are an independent agency, we work for you, not the insurance company. We explain your general liability options in plain English or Spanish, help you avoid the common mistakes below, and stay with you at claim time. Visit us at one of our three Georgia offices in Duluth, Lawrenceville, or Gainesville, or get a free quote by phone.
Informational note
This guide is provided for general educational purposes and reflects rules and figures known as of 2026. Insurance laws and carrier programs change — for advice specific to your situation, speak with a licensed TOP Insurance agent.
Frequently Asked Questions
Do landscapers need workers' comp in Florida?
Yes, if you have one or more employees (construction). Machinery, heat, and cutting injuries make this coverage essential.
Is my equipment covered if it's stolen from a trailer?
With inland marine (equipment) coverage, yes — it protects mowers, trimmers, and tools on-site and in transit. Standard liability does not cover your own equipment.
Do I need special coverage to apply herbicides?
Often yes. Chemical application is frequently excluded from standard general liability, so you may need a specific herbicide/pesticide endorsement.
What insurance do commercial landscaping contracts require?
Most require general liability and, if you have employees, workers' comp — usually with the client named as additional insured on a Certificate of Insurance.
Get a Free Florida Quote Today
Ready to protect what matters most? Our bilingual team makes it easy. Request your free, no-obligation quote and let a licensed agent compare your options in minutes. Explore our coverage options, learn more about insurance in Georgia, Florida, and Texas, or contact us today. Call 1-877-579-0587 or message us on WhatsApp at 1-470-429-0756.

TOP Insurance LLC is a licensed independent insurance agency serving Georgia, Florida, South Carolina, Tennessee, Alabama, Indiana and Texas. Our bilingual team of licensed agents compares options from several carriers to find an alternative that fits your needs and budget. With offices in Duluth, Lawrenceville and Gainesville, GA, we specialize in auto, home, life, health and commercial insurance for the Hispanic community and all residents. Some carriers may offer options for applicants with an ITIN, consular ID, foreign passport or foreign license; required documentation and eligibility depend on each carrier.
Ready for your free quote?
Our bilingual agents help you compare options from multiple carriers to find an alternative that fits your needs and budget. Same-day response, no obligation.
